Reduce Your Tax Liability,

Boost Your Savings.

Comprehensive Tax Planning & Management Solutions for Individuals, Entrepreneurs, Professionals, and Businesses.

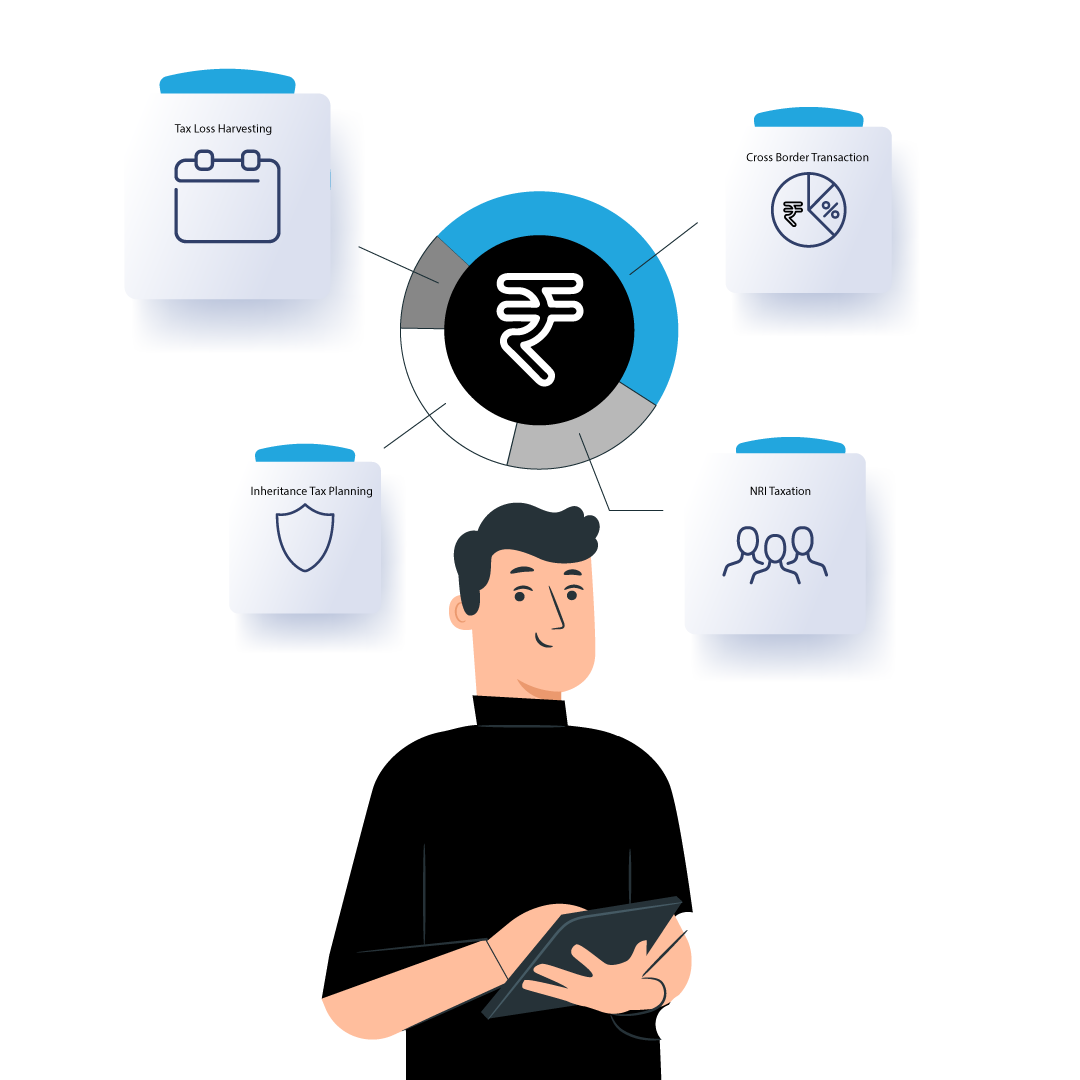
Our seasoned team of chartered accountants and tax consultants excels in offering comprehensive and ethical regulatory and tax management advisory services. We specialize in advanced tax planning, cross-border taxation management, family office management, and provide a wide range of services, including:

  • Tax Loss Harvesting
  • Inheritance Tax Planning
  • Cross Border Transaction

Customized Tax Planning Solutions for Individuals, Entrepreneurs, Professionals, and Businesses.

Comprehensive Tax Planning with Expert Insight

Leveraging our in-depth expertise and knowledge, we provide comprehensive tax planning solutions that go beyond just tax savings. Our approach allows you to strategically manage your taxes throughout the year, fostering long-term wealth creation

Tailored Tax Solutions to Match Your Unique Situation

Recognizing the individuality of your income, expenses, and tax structure, we craft entirely bespoke tax plans. These personalized solutions not only help you meet your tax-saving objectives but also establish a solid foundation for pursuing your financial, retirement, and wealth creation goals with precision and accuracy.

Frequently Asked Questions

How can I save Income Tax?

You can save income tax through legal methods such as investing in tax-saving instruments, claiming deductions, and optimizing your financial portfolio.

Do I need to change my existing tax planning strategy?

It depends on your current financial situation and goals. Consult a tax advisor to determine if adjustments are needed.

Does tax planning mean tax avoidance or tax evasion?

Tax planning is legal and ethical. It aims to minimize tax liability using legitimate methods. Tax avoidance is legal, while tax evasion is illegal.

What methods are available to minimize my tax obligations?

Methods include investing in tax-saving options (e.g., PPF, ELSS), claiming deductions under various sections (e.g., 80D, 80G), and optimizing tax-efficient investments and financial planning. Consult a tax expert for personalized advice.

Smart Tax Saving Tips for Every Indian

Effective tax planning is not just about saving money at year-end — it is an ongoing process that, when done right, can significantly increase your take-home wealth. Here are key strategies our advisors recommend to maximize your legal tax savings every financial year.

1
Maximize Section 80C Deductions

Section 80C allows deductions up to Rs 1.5 lakh per year through investments in ELSS mutual funds, PPF, NSC, tax-saving FDs, life insurance premiums, EPF contributions, and children's tuition fees. Invest early in the financial year rather than rushing at March-end to also benefit from returns throughout the year.

2
Claim Health Insurance Deductions Under 80D

Section 80D provides deductions up to Rs 25,000 for health insurance premiums paid for yourself, spouse, and children. You can claim an additional Rs 25,000 to Rs 50,000 for parents depending on their age. This is a deduction over and above the 80C limit, giving you significant additional tax savings while ensuring your family is health-protected.

3
Invest in NPS for Additional 80CCD(1B) Benefit

The National Pension System (NPS) offers an exclusive additional deduction of Rs 50,000 under Section 80CCD(1B), completely over and above the Rs 1.5 lakh 80C limit. This means you can effectively reduce your taxable income by up to Rs 2 lakh just through 80C and NPS combined, making it one of the most tax-efficient long-term savings instruments available.

4
Claim HRA and Home Loan Benefits

If you live in a rented house and receive HRA as part of your salary, ensure you claim the full HRA exemption by submitting rent receipts to your employer. If you have a home loan, the principal repayment qualifies under 80C, and the interest paid is deductible up to Rs 2 lakh per year under Section 24(b), significantly reducing your taxable income.

5
Choose Between Old and New Tax Regime Wisely

The new tax regime offers lower slab rates but removes most deductions. The old regime allows all deductions including 80C, 80D, and HRA. The right choice depends on your total deductions — if your eligible deductions exceed Rs 3.75 lakh, the old regime typically saves more tax. Our advisors compare both regimes for your specific income and deduction profile during tax planning sessions.

Tax Planning - Frequently Asked Questions

The old tax regime allows you to claim various deductions and exemptions like 80C, 80D, HRA, LTA, and home loan interest, reducing your taxable income before applying slab rates. The new tax regime provides lower tax slab rates but largely eliminates these deductions. Individuals with substantial deductions may save more under the old regime, while those with few deductions benefit from the simpler new regime with lower base rates.

Section 80C allows a deduction of up to Rs 1.5 lakh per year for investments including ELSS mutual funds, PPF, EPF, NSC, tax-saving FDs with 5-year lock-in, life insurance premiums, Sukanya Samriddhi Yojana, home loan principal repayment, and tuition fees for up to two children. ELSS offers the shortest lock-in of 3 years among all 80C options and potential for higher returns.

Yes, NPS is one of the best tax-saving instruments available. Apart from the Rs 1.5 lakh deduction under 80C, contributions up to Rs 50,000 additionally qualify under 80CCD(1B). This exclusive Rs 50,000 deduction is available only for NPS and is over and above the 80C limit. NPS also builds a retirement corpus that provides regular pension post-retirement, making it both a tax saver and a retirement planning tool.

Tax planning should begin at the start of the financial year in April itself rather than at year-end in February or March. Starting early allows you to spread investments across the year through monthly SIPs in ELSS, enjoy returns on your tax-saving investments throughout the year, and avoid the stress of last-minute decisions that often lead to suboptimal product choices made purely for tax saving without considering returns.